-
The private placement deal was a huge leap in value from its inaugural securitization in October 2024, when it raised $150 million.
 September 24
-
The move solidifies the convergence of securitization, and the techniques that make the deals operate, with other financing solutions.
September 24
-
The deal's obligor concentrations—its top and top five obligors account for 9.45% and 37.95% of the pool—are reigned in by WEF's focus on mission-critical essential use equipment.
September 21
-
GDLP 2026-2 also has lower levels of initial credit enhancement compared to GDLP 2026-1, at 6.12% versus 5.74%; overcollateralization at 23.90% versus 24.92% and total gross excess spread of 5.55% versus 5.98%.
September 18
-
To keep cash flowing to the notes, the deal's senior notes have an interest reserve account covering three months' worth of class A note interest payments and fees.
September 17
-
ODAS IV 2026-1 will issue expandable term notes, so that at any time during the revolving period the issuer can periodically upsize the notes to a maximum of $626 million.
September 15
-
If a cumulative net loss ratio amortization event occurs, then Reach 2026-3 will enter full turbo mode, a phase when the transaction will use all available funds to sequentially pay down the outstanding notes.
September 10
-
The series AFRMT 2026-4 and AFRMT 2026-5 have virtually identical capital structures, but have legal final maturity dates of Sept. 17, 2035, and Sept. 15, 2037, respectively.
September 9
-
The 2026-B notes have a total initial hard credit enhancement of 10.00%, compared with 9.60% from the previous deal, the 2026-A.
September 8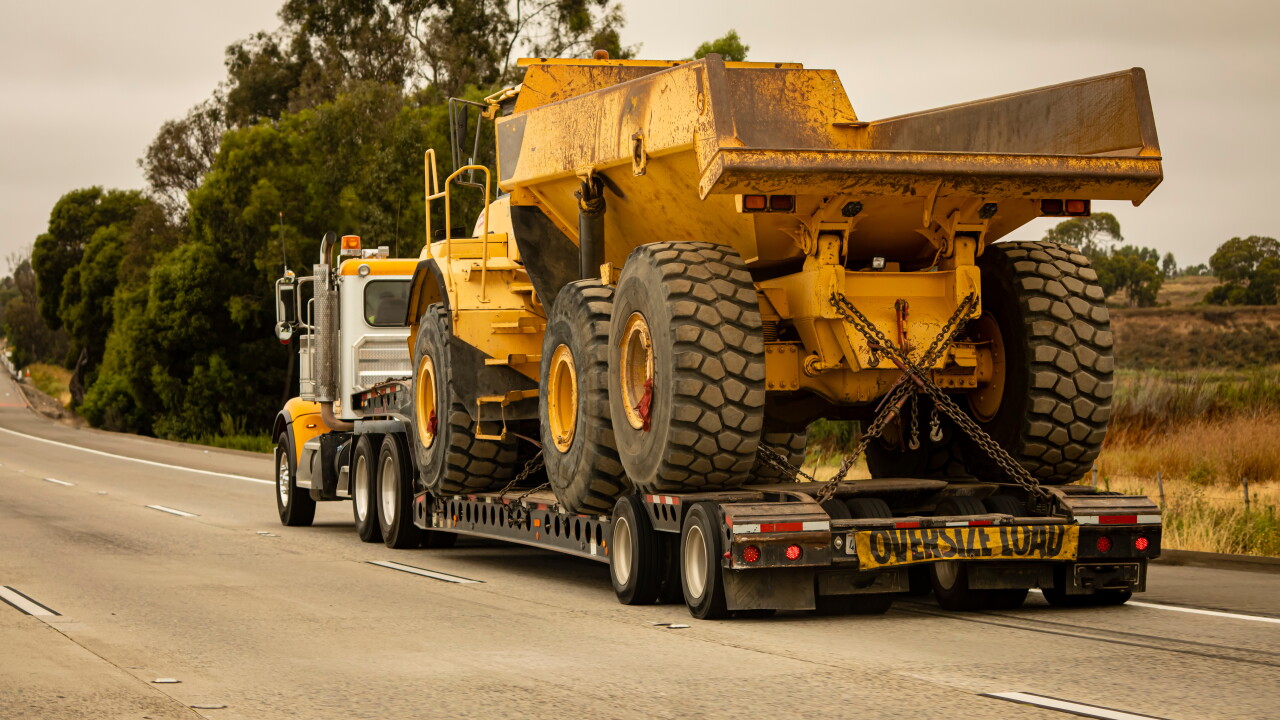
-
Some investors have looked to buy only shorter-term commercial paper from Guggenheim, while a smaller portion of backers have paused trading the firm's products
September 8
-
The deal is backed by recently originated, 30-year fixed-rate mortgages with an average combined loan-to-value ratio of 75.1%, according to Morningstar DBRS.
August 28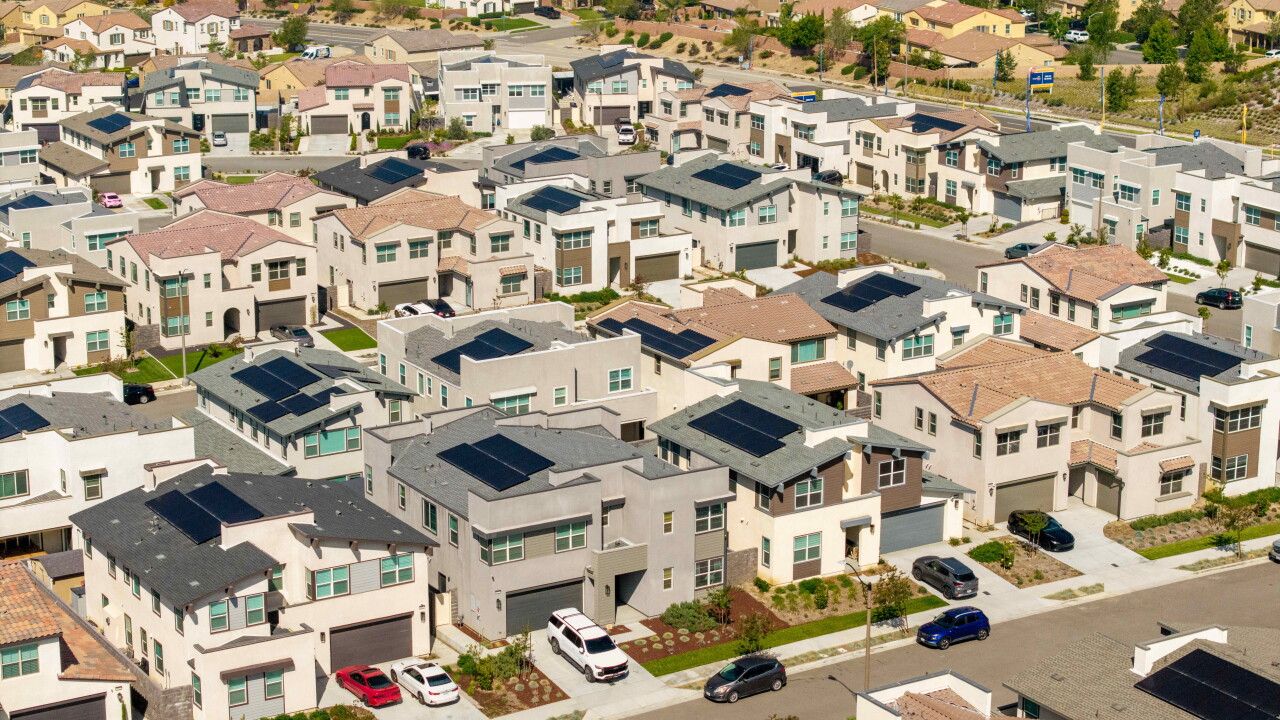
-
All loans in the deal's portfolio were made to investors and underwritten based on property cash flow and rental income to determine borrower eligibility.
August 27
-
The transaction's pool includes roughly 2.4 million square feet of office space, or 94.6% of the total, on the first through 60th floors.
August 26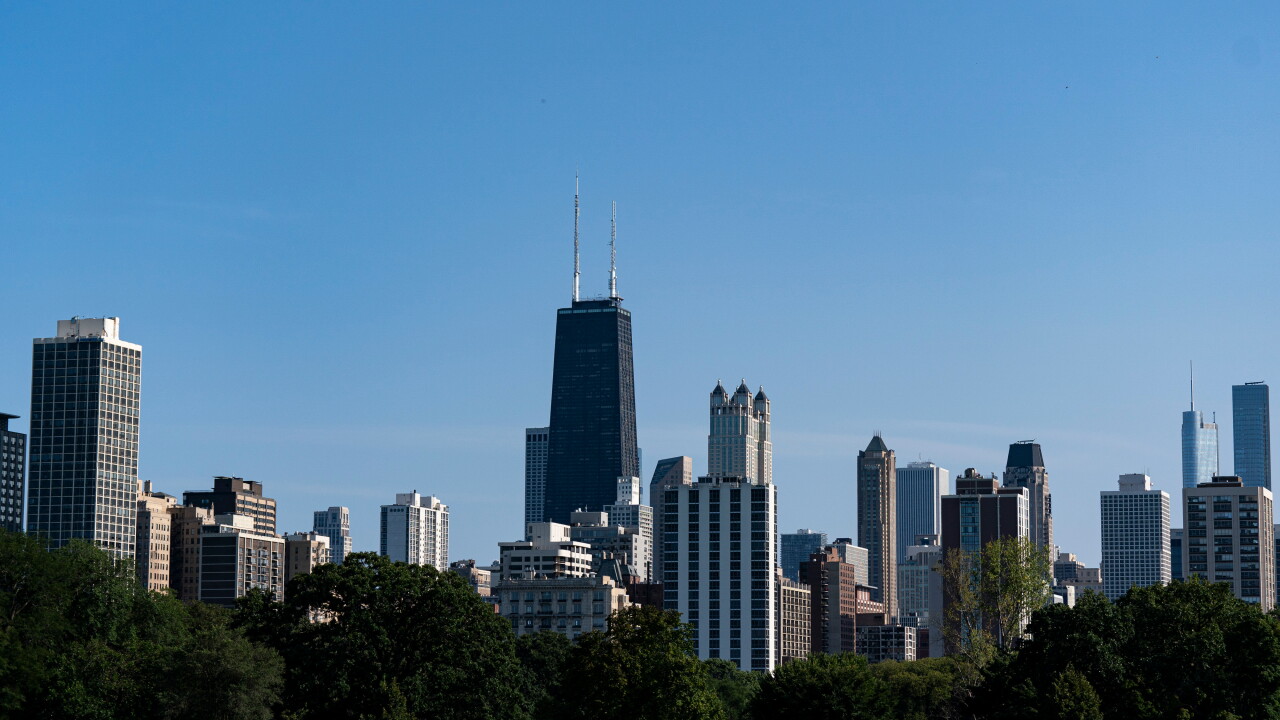
-
Non-prime loans comprise 72% of mortgages backing CROSS 2026-NQM10 Mortgage Trust, with most of them fixed-rate.
August 26
-
The deal's structure includes debt service coverage ratio (DSCR) triggers that will deposit excess cash is deposited in the cash trap reserve and loan-to-value tests.
August 14
-
Interest will be repaid sequentially. Scheduled principal will be paid based on the scheduled outstanding note balance for the applicable payment period and the note balances.
August 4
-
Equipment loans and leases that Redaptive Sustainability primarily acquired from originators, will back the asset pool.
July 24
-
The transaction will repay senior fees, principal and interest on the A1 class before repaying monthly interest on all remaining outstanding classes of notes.
July 22 -
The top 20 obligors account for 32.0% of the aggregate securitization value, while the top 10 represent 18.8%, a moderately elevated concentration.
July 21
-
SLR series 2026-1 benefits from initial overcollateralization of 8.00%, with a target of either 13% of the pool's aggregate ABS value or 8.00% of the securitization value on May 31.
July 20