-
The deal also includes a 120-day stop advance provision, which prevents it from forwarding any interest and principal on loans that are past 120 days delinquent.
 May 22

-
The transaction's debt service coverage ratio (DSCR) was calculated from a three-month lookback window of cash flows, shorter than the ABS transactions pre-COVID 19.
May 21
-
Lenders pulled back on commercial real estate loans in 2023, as high interest rates put pressure on property values. They're now returning to the sector, and the renewed competition is prompting a pricing war.
 May 21

-
The market for so-called collateralized fund obligations could top $30 billion of new volume this year, up 50% from last year.
May 21
-
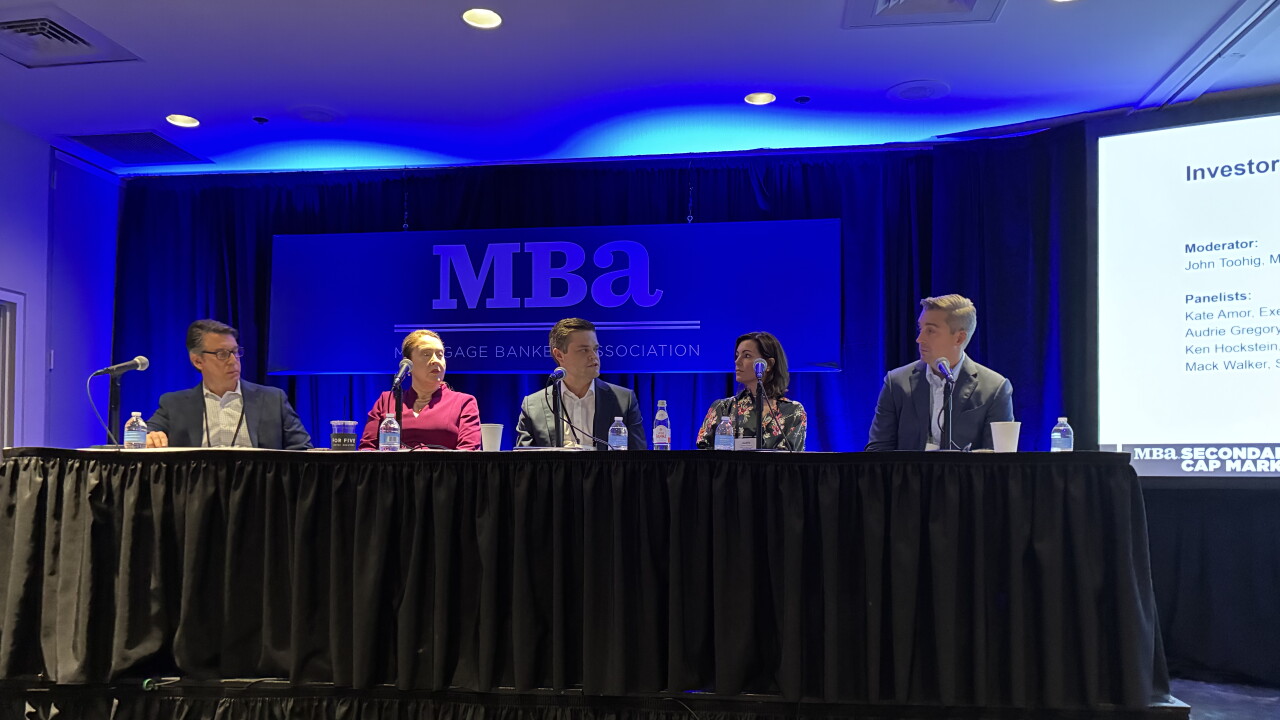
Lenders at the MBA conference say non-agency is more than just non-QM — and those still treating it as a niche product are falling behind as it becomes a core part of the business.
 May 21
-
The deal has a two-year revolving period, scheduled to end in June 2028, when collections from the asset pool can be used to purchase new economic participations.
May 20
-
As lenders explore the adoption of FICO 10T and VantageScore 4.0, setbacks and data limitations remain.
May 20
-
Three tranches of notes will be issued to investors, and the A2 tranche will issue the bulk of the debt, $613.7 million. Also, the notes have an anticipated repayment date of June 2031.
May 19
-
Lenders are finding better economics by placing agency loans into private-label securities, depending on the particular situation.
May 19
-
Department of Housing and Urban Development officials indicated that there are improvements in some delinquency stages and cure rates are better than expected.
 May 18

-
Secondary market experts are split on whether the Fed's next move will be a rate decrease in 2027 or an increase, as more observers are now thinking.
May 18
-
Standard & Poor's found modeled foreclosure frequency and loss coverage to be in similar ranges as classic FICO but showed concern about potential bias.
May 15
-
The cumulative advance rate on the notes include range from 68.5% and 87.7% on the A1 notes and A2 and A notes, respectively.
May 15
-
S&P sets an estimated cumulative net loss of 2.85% for the CRVNA 2026-P2 notes, unchanged from the CRVNA 2026-P1, because the collateral characteristics were unchanged.
May 14
-
On an end-to-end basis, the joint initiative delivers collateral without relying heavily on manual transfers as loans are settled, then transferred between institutions.
May 14
-
Notes will amortize sequentially to allow cash to be released to the issuing entity on a limited basis if it maintains the overcollateralization target.
May 13
-
The International Finance Corporation, has agreed to insure the credit risk on a $500 million portfolio of trade finance tied predominantly to low-income and conflict-affected countries.
May 13
-
Consumer Credit Portfolio II is not a securitization, but Groundfloor is known for two deferred-pay residential transition loan ABS that are paying investors higher premiums than rated RTLs.
May 13
-
If principal and interest DSCR falls below 1.75x, then 50% of all excess cash flows will be deposited into the deal's cash trap reserve account.
May 12
-
The underlying asset pool is heavily concentrated in narrowbody aircraft models, mostly A320-200s, with large, in-service fleets and broad operator bases.
May 12